Mobile Payment – Thoughts after listening

Thoughts resulting from The webinar Doug King of the Atlanta Federal Reserve gave on “Future Proofing Payments”

The long standing question of the future of Mobile Payments, again discussed and again similar conclusions.

  • Will the American market embrace the idea of mobile payments?
  • Is it a question of when or a question of why?
  • Why do emerging markets embrace new ways and mature markets resist?
  • Is it all about acceptance and the merchants investment in contactless reader capability?
  • Is it an all or nothing concern?
  • Could it be simply reality, as ling need our wallet with other cards e.g. our drivers license, why eliminate payment cards from the physical wallet?

Doug touched on all of these questions. He shared relevant statistics demonstrating the slow and possibly indistinguishable grow in usage of mobile wallets. He shared the success of several of the merchant proprietary mobile payment approaches.

Which leads me down the path of another question. What is the value proposition that will ignite the use of our phone and devices as carriers of our means of payment? The possibility to create value simply with a electronic wallet carrying only means of payment, does not create an exciting proposition.

Our mobile phones and connected devices provide us with such value

We have embraced dozens of apps. They help us to navigate, shop, explore, play and learn. Our phones are beginning to become security devices, taking advantage of sensors to integrate biometrics into how we access and authenticate ourselves as we browse and explore the ever increasing digital place we now call cyber space.

There is another phenomena emerging as a result of how we are transforming how we engage. Some called it the “Uberization” of payments, the ability to make payments frictionless. A change so profound we must stop and reflect and ponder what next.

I recognize there is a repetitive theme to my musing.

When physical world merchants fully embrace the concept of omni channel and build their virtual and physical experiences to complement and augment one another, then, with the ability to integrate payment seamlessly into the shopping experience a value proposition emerges.

What is EMVCo goal with the release of their SRC framework

October 2017 EMVCo published version 1.o of their Secure Remote Commerce Technical Framework.  Today I decided to read and appreciate what they are trying to accomplish and then consider how it ties into what I remember and think we need to do moving forward.

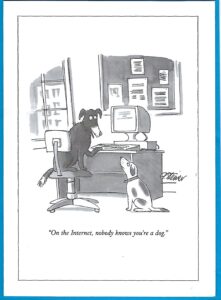
Clearly the challenge links back to the now infamous New Yorker Cartoon.  We have not successfully established a means of assuring the identity of an individual when presenting payment credentials (the PAN, Expiry date, name, billing address and CVV.  The first attempt, still not 100% implemented, was the introduction of CVV2, CVC2 or CID a 3 or 4 digit number printed on the back or the front of the payment card.

We then developed something called SET or Secure Electronic Transactions and unfortunately the payment networks were not willing to allow Bill Gates and Microsoft to earn 0.25% of every sale for every transaction secured by SET he proposed to build into Microsoft’s browser.  Without easy integration into the consumer browser, the challenges of integrating SET into the merchant web pages and the Issuer authorization systems caused this effort to fail the death of some many other noble but complicated attempts to create a means of digital authentication.

Next came 3D-Secure, a patented solution Visa developed.  It offered what was considered a reasonable solution to Cardholder authentication.  Unfortunately, given the state of HTML and the voracious use of pop-ups, the incremental friction, led to abandon shopping carts and consumer confusion.  Another aborted attempt at Internet fraud mitigation.

Yet 3D-Secure was not a total failure.  Many tried to enhance it, exploit it and avail themselves of the shift of liability back to the Issuer.  Encouraging consumer engagement and adoption was futile in some markets mandated and cumbersome in others.

Now let’s consider what EMVCo is attempting to do with their Secure Remote Commerce Technical Framework.  As I started to read, I ran into this:

“As remote commerce becomes increasingly targeted and susceptible to compromise, it is important to establish common specifications that protect and serve Consumers and merchants.”

Clearly the authors do not have institutional memory and cannot remember the various attempts alumni of these same organizations spent time on and encouraged many to invest in their implementing.  Clearly this lack of historic context will leave some pondering the purpose of this paper.

I then read this sentence and reflect back on a recent hearing on “Social Security Numbers Loss and Theft Prevention” in front of The House Ways and Means Subcommittee on Social Security

“Over time the Consumer has been trained to enter Payment Data and related checkout data anywhere, making it easy for bad actors to compromise data and then attempt fraud.”

Once again, I stand  troubled by how the Payment Data clearly printed on the face of the card and especially the PAN, 11-19 digits, designed to simply be an identifier, was converted into an authenticator.  Like the social security number, the drivers license number, the passport number and your library card number, the PAN and other “Payment Data” was never designed to be an authenticator.  It was meant to be data a merchant could freely record.

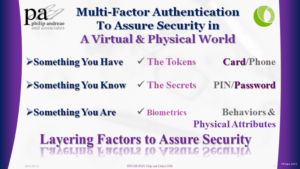
The secure features of the card now the EMV cryptographic techniques otherwise referred to as the Application Request Cryptogram “ARQC” were meant to offer the “What You Have”  factor in a multi-factor authentication scheme.

As I began to appreciate the scope of this document, the term “Consumer Device” becomes critical.  I began to wonder if a PC is a consumer device or if a consumer device is only something like a mobile phone, watch or other like appliance.  Fortunately, later in the document, the definition clears up any confusion created by the earlier use of this term..  This said, I then wonder about the difference between what they define as Cardholder Authentication and Consumer Verification?

After reading through all the definitions, I ponder why the authors had to change terminology?  Why could they not embrace known and recognized nomenclature.  Do we need a new vocabulary?

I wondered:

If this is another attempt to create a revenue stream for the payment networks?

Or, is this the effort of a “closed standards” body to reduce the potential value of the W3C WebPayments activity?

 In search of an answer to this last question, I found this discrete comment inside the SRC FAQ.

9. Are any other industry bodies working in this area?

EMV SRC is focused on providing consistency and security for card-based payments within remote payment environments.

EMVCo aims to work closely with industry participants such as W3C to capitalise on opportunities for alignment where appropriate.

Having read bits and pieces of this and the WebPayments efforts one does wonder what is EMVCo trying to do.  We shall see?

Why do we need Tokens and Tokenization

Recently I was directed to a link http://paymentsjournal.com/tokens-work-because/ and wanted to write the author Sarah Grotta.  As I wrote the message crystallized in my head and maybe as this prior post already discussed, this idea of tokenization made me cringe.

I contend that Tokens exist because we turned the PAN Personal  / Primary Account Number, like we turned the SSN Social Security Number, into an authenticator.  One can must ask the question.  How can a random value (an identifier) become an authenticator and remain secure?

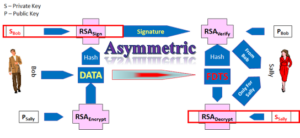
EMV works because it renders the Card unique, hence addressing the question of counterfeit, by employing the first factor of the classic MFA Multi-Factor Authentication concept “What You Have”.  EMV defined a common set of secrets and digital credentials; securely stored in a Secure Element or Chip Card.

We here in the United States decided not to implement the second factor, the Personal Identification Number or PIN, for a variety of reasons. Hence, why Lost and Stolen remains an issue or weakness in the American Card Payment environment.

Biometrics are emerging and could solve for the assurance of cardholder presence.  The challenge is how to effectively (cost and convenience) locate the biometric sensor and facilitate the matching of the sensors output to the persons registered biometric.  Let alone, how does one make sure the right persons biometric was registered and associated with the device.

In the mail order / telephone order, now cyberspace, we did not replicate merchant authentication, the first factor – “What You Have. The card, once was secured with things like the magnetic stripe, using CVV1, the Hologram and the other physical features.  We simply shifted the liability to the merchant and called it a “card not present” transaction.

People can claim all sorts of goodness because of tokenization.  They can talk about how the EMVCo’s tokenization framework describes the use of tokens in device and domain specific scenarios.  All of this, an issuer, could have done; if they, like some did, simply issued another number, a PAN, to the wife, bracelet, watch, ring or whatever other permutation they deemed appropriate.  They can talk about dynamic data.  yet what they often forget to include when they use the words “Dynamic Data” they are really talking about a cryptographic value as described in EMVCo Book 2.

Yes, this does mean the question of how the PAN and its digital credentials get deployed; has to be addressed.  This said, GSMA with EPC did offer some thoughts, last decade, when they described the Trusted Service Manager

Instead handset oligopolies replaced the MNO with the their Mobile Pay wallets.  They working with the Payment Networks and focused on control and the creation of income.  They, as monopolist will, have created barriers, restricting others from offering comparable services.  The TSP now becomes this restrictive service that guarantees the power of companies like Apple and Google, supported by their friends, the payment network operators.

The original article also spoke of the PAR; another data element merchants, processors and the industry, will have to invest in supporting.

I ask the question.

If we had assured the authentication and verification of every payment transaction
Using Multi-Factor Authentication
Why did we need to turn the PAN into a dynamic value? 

My contention, simply use the appropriate level of  cryptography.

If the Issuer or their processor is in control and understands basic EMV and Cryptography, then securing the PAN is not an issue.

Consider household financial management.  If each member of a household has a unique PAN; budget, tax preparation and understanding who spent what where is a lot easier.  The husband,wife and children should have their own unique PAN, stored in the clear in their devices and on their card.

The real requirement, my personal devices, including my payment card, simply need to be linked to one PAN their Personal Account Number, associated with the individual.  The PAN Sequence number could easily allows each device to be uniquely identified, if necessary.  The card and devices becomes the carrier of your identifier.  A thing that can be authentication as something you have.

Here is where the second factor comes in.  Is the person presenting the PAN the rightful and authorized individual? All this required, is assurance to the shareholders that the presentment of the PAN is a unique and authorized event.  This is best achieve by using either something you know or something you are to bind the individual to the instrument carrying the Identifier.

Yes, a bit of friction to assure the  consumer they are securely paying for what they want to buy

Since the World Wide Web came of age and merchants saw its potential.  The question of how to secure the Card Not Present space, this question of cardholder presence, has not been properly addressed.  Visa and MasterCard (when they were not for profit associations) created the utility of the Card Verification Result CVV2, CID or CVC2 which would be printed on  on the card and not part of the magnetic stripe, the problem the bad guys could still steal the card or get hte card number and capture CVV2..  MasterCard and Visa then created SET, 3D-Secure and now, as for profit owners of EMVCo, are proposing, maybe even will mandate, the industry implement EMV 3D-Secure.

Each, an attempt to provide some means of Authentication and Verification.

Each introducing a level of friction as a means of security.

This is the problem.  The market did not start by emphasizing the need for security by educating the consumer.  The industry needed to help the consumer understand they should care and want to securely pay for what they intend to buy.

Instead:

  • The Zero Liability Policy was adopted.
  • The merchant was more than happy to sustain a degree of lose (fraud) in exchange for sales and profits.

The result, as all anticipated would happen, was blissfully ignored and eventually they cried out about.

Fraud migrated to the weakest point
Just like water finds its way to the lowest point. 

EMV, introduced in the Face to Face card present environment, pushing the bad guys: be they criminals, state actors and terrorists to find alternate another channels for their financial gain.

EMV and now the recently published WebAuthN and FIDO specifications create effective mechanisms for Consumer Authentication.

Let us please remember – the PAN, a user name, your social security number or your email address are excellent Identifiers.  They should not be authenticators and they are not a means of “Identification”.

Let us also remember, the term Identification means that one is assured of the irrefutability of identity.

The big question:

  • Why did we have to get rid of or replace the PAN?
  • Why did we and continue to need to invent and invest in all this addition overhead?
  • Why did we not simply address authentication?

Some will argue the challenge of using the PIN or a Password, as a means of Verification, is because it is to hard to remember. Especially, if each password people use to access website, services, building, has to be unique.  Some will argue imposing friction to add security is not convenient.  Others will remind us that security is and has been a necessity since the beginning of time.

Why didn’t we when we created this great new digital shopping mall?

Bottom line each of the devices used to present or acquire the PAN, must be capable of authenticating the identity of the authorized presenter, in both the physical and virtual world.

At least these are the views of someone who believe history provides a baseline for tomorrow and tomorrow must be designed as a function of where you want to be, knowing where things came from.


A message unsubscribing to https://act.moveon.org

I agree with the actions you are all taking, yet. I am not a democrat nor a republican. Constantly begging me for a donation creates friction.

When a party emerges that is in the middle and represents

  • The fiscal values by focusing on the PEOPLE not the lobbyist, billionaires and companies with deep pocket.
  • The social responsibilities including but not limited to universal healthcare, the economy, equal education and the environment.

When these values which I hold dear become the focus on a party, then maybe.

All I see today is Greed, Pride getting in the way of common sense and mutual respect. All I hear is ugly noise from both parties. I see a city frozen. The election of President Obama created a racial divide. Washington now smelling like a cesspit, not just the swamp Trump spoke of.

We, through our electoral system, elected Donald Trump.

Am I happy

  • With the mess he has created with taxes, the economy, tariffs, immigration, the courts
  • With how he is treating Canada, Europe, Mexico and so many others
  • With what he has done to international treaties and trade
  • With his denial that humans have and do effect the planets environment climate Change is real

No!

Does it bother me that:

  • He is coddling the strong men of this world like Kim, Putin …?
  • The consequences of tariffs on Global trade are not part of the dialogue?
  • We do not understand the USA is no longer a manufacturer
    • We are a place where innovation drives invention.
    • We are a service economy and must focus on keeping these jobs here.

YES

Let him get on with doing his job. Yes the legislator must do its job and make sure we have a check and a balance. We must restore order and civil discourse.

That said, the press needs to spend less time talking about him. Yes, the press must do its job and be allowed and pushed to continue to do its job. They should highlight what is being done and what some think. But hours of talk only makes the divide wider. Today for any sensible individual to understand the reality one must watch BBC, CNN, FOX, CBS, PBS, NBC, and how many others to filter truth from spin.

We must restore respectful dialogue.

“Do not conform any longer to the pattern of this world, but be transformed by the renewing of your mind.”
Romans 12:2

is this what it is really all about

June 25, 2018 I read this opinion piece –

White Extinction Anxiety – https://www.nytimes.com/2018/06/24/opinion/america-white-extinction.html

And I reflected on the CBS News article my colleague sent me The message “86-ing” Sarah Sanders sent to conservatives – https://apple.news/AFUXCTyw5RS668F_2_ElK0A

When he and I we spoke earlier today, the following statement created the impetuous to write. He said the Sanders incident was “the step to far” I would argue it is simply another step in the wrong direction. Have we stepped over the line? Maybe yet all we have to do is read @realDonaldTrump tweets to wonder where the line is. I then think about:

  • The incident in Colorado, due to a difference in religious beliefs.
  • What happened as a result of white supremacists marching in Charlotte last year.
  • What is happening in restaurants in the DC area.
  • What is happening along our southern and northern borders.
  • What has happened to our legislator and our two-party system.
  • Trump and other conspirators issue over Obama and his place of Birth.
  • Pro-life versus woman’s rights.
  • The puritan right versus the socialist left.
  • Urban versus rural dwellers
  • Globalists versus nationalists
  • The issues of Palestine, Jerusalem and the Sunni Shite divide.
  • Pakistan, Israel, India, North Korea, Libya, Iran and all those others who sought, acquired or are seeking the power of the Atomic bomb.
  • Capitalism gone terribly wrong, with off-shore labor arbitrate killing American Jobs.

Adam Smith, I think, spoke in respect to a village economy. What I will call a closed system. Yes, this village can be free market. It is the ability to separate and push, that which is not part of our village, out; that defeats the equity built into that village.

This is further complicated by the divide between the rich and the poor, between the haves and have not and now between the Republicans and the Democrats. I could have spoken of race: Angle Saxon versus African versus Asia versus Japanese or Chinese and I am sure we could add a myriad of other point of contention. The issue is we are becoming less divided not more

It feels like we have devolved into a world that thinks – “If you are not one of us you are not my neighbor. How then do we find and restore balance? How do we merge these two Christian thoughts into one?

“The first is, ‘Hear, O Israel: the Lord our God, the Lord is one; you shall love the Lord your God with all your heart, and with all your soul, and with all your mind, and with all your strength.’ The second is this, ‘You shall love your neighbor as yourself.’ There is no other commandment greater than these.”

“How can Satan cast out Satan? If a kingdom is divided against itself, that kingdom cannot stand. And if a house is divided against itself, that house will not be able to stand. And if Satan has risen up against himself and is divided, he cannot stand, but his end has come.”

Earlier I was going to use the word Jihad. When I looked to the definition I had to hold that thoughts and use it in a different and more informed way. If I look at the two definitions 1. is what I planned to speak of. While 2. is what all of this is about.

Definition of jihad

  1. a holy war waged on behalf of Islam as a religious duty; also:
    a personal struggle in devotion to Islam especially involving spiritual discipline
  2. a crusade for a principle or belief

When Obama came into office our legislators found every reason not to work together. The Tea party emerged. The left drifted farther left.

Hillary divided this nation. There were those not willing to see the Clinton dynasty survive. There were those who wanted to turn inward, a protectionist state. There were those afraid of the future and the implications of the Fourth Revolution. There were those who did not believe in any form of social welfare, be it universal health, education or wealth.

All of this leaves me adrift.

Sunday, thinking of being in the boat in a storm

Listening to Brian our minister speak of today’s reading, he speaks of the challenge of the storm, we today, are surrounded by a storm set alight by division, fear and the confusion of what next.

Brian speaks of the love within. That love that rests inside each of us. He spoke if how we are turning away from religion.

This led me to ponder the demise of the gentle spirit Jesus tried to instill and restore in each of us. This thought often takes my heart to remembering how Jesus condensed the ten commandments down to two.

“The first is, ‘Hear, O Israel: the Lord our God, the Lord is one; you shall love the Lord your God with all your heart, and with all your soul, and with all your mind, and with all your strength.’ The second is this, ‘You shall love your neighbor as yourself.’ There is no other commandment greater than these.”

We have lost sight of this need to respect each other. We are torn apart by our differences. We are intolerant and believe we know better. We are divided as to our fiscal and social responsibilities.

The Lords and Masters who stand over us, insight dissension, foster racial attitudes, lie, and corrupt. Comedians, newscasters, authors and pundits make fun of the situation we are in.

Yet the sting of reality persists.

Of NFC, Mobile and History

Today I read Karen Augustine’s  Mobile Payments Use in the U.S. Lags

As I read and reflected on what Karen wrote, I reflected on my experiences as a sagged payment consultant and executive, with international experience.

What I see is an issue of legacy and muscle memory – setting a pattern for the future.  Said another way – our history defines the boundaries of our future.

Asia did not have electronic payments.  I am sure did not want to embrace the globally dominate American solution.  Therefore, they had the opportunity to start fresh.  It is very much like what Spain went through, went they moved from cash to electronic card-based payments.  They bypassed the check.

Her article brings back memories of life in Belgium in the 90’s.  Writing a check was a rare occurrence.  Direct debit mandates, a MisterCash card and a Eurocard was all we needed to buy and enjoy life.  Electronic payments was the norm, paper checks were a rare oddity and cash, well yes there was a very present grey economy.

Here in the USA we developed our payment systems off the back of regional or state banks with acceptance networks limited to a local domain.  Moving to a national system required early adoption of a common national currency.  We then went on to replace IOUs with paper checks and store cards with credit cards.  In time we enhances the ACH system and developed support for remote deposit and check capture.

Why do we need to move the card into the wallet?  Why change habits that are comfortable and work?  Most of us drive to shop and therefore must have our drivers license.  We must carry a physical document with us.  We simply carry two or more ID-1 sized cards.

You make the statement and was once again reminded of times past.

“… universal mobile wallets and more often driven from merchant based applications that often incorporate loyalty and rewards, which to date still remain nascent in universal mobile wallets.”

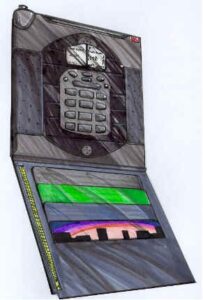
When I produced this rendering, back in 1996, I was on stage talking about a world where leather and technology converged.  I imaged Bluetooth, NFC, secure elements, GPS and our various credentials converging into this personal device.  Those credentials grouped into: travel, identity, membership, loyalty and payments; easy to find and present.

When contactless payments were  introduced, in 2004, by Visa’s with PayWave and MasterCard’s PayPass; I argued why contactless cards – how can the issuer afford the extra dollar per card (cost of the antenna and inlay) and the merchant the extra 60 dollars to enable the NFC reader?  The way Issuer income works, “Interchange”, the consumer would need to spend more on that issuer’s card.  For the merchant to justify the necessary POS investment, meant the retailer believed the consumers would spend more, because it was “easier”.  Was Tap To Pay going to make me spend more.  Maybe for small ticket purchases, I may use cash less; but at the merchants expense!  We argued the cost of cash was more than the Merchant Discount.  Some agreed.  Many wondered what the blank are they trying to sell us!

Around the same time America was exploring this contactless experience, the European Payment Council and GSMA debated and ultimately offered an approach for mobile card based contactless payments https://www.europeanpaymentscouncil.eu/sites/default/files/KB/files/EPC220-08-EPC-GSMA-TSM-WP-V1.pdf .  Handset manufactures like Nokia had already added NFC Antenna’s to their mobile phones and mobile network operators, the MNO, saw the SIM as the secure element capable of holding payment credentials.

Some tried, the Trusted Service Manager as a service was developed and deployed.  The challenge, the economics of the model.  In this case the MNO saw revenue and wanted to charge fees to load the payment credential into the phone and better yet charge rent to store these payment cards in our phones.  Again I ask the question, by changing the way we pay, do I cause us to want to spend more? I think not!

Maybe some would argue, with  a credit card people am able to buy things today that they cannot afford.  Let them end up in debt.  This is true.  But then is debt  at 18% a good thing?  Europeans simply decided to establish a line of credit, as a feature of a Current Account, at reasonable interest rates.

We could go on and talk about how Apple saw the possibility of a 0.15% income stream from ApplePay based mobile payments and how the EMVCo tokenization framework evolved to support their desire to protect the Apple Brand.

What is clear, we could solve George’s problem and replace his Full Grain Vegetable Tanned Cow Leather leather wallet with a Mobile Wallet managed by Apple, Google, Samsung or …

Or, we could think about the consumer and what they really want?

As your article made clear, and so many others have shared, Asia leaped forward.  Be it AliPay or WeChat, the device, the mobile phone, became the consumers wallet, their method of engaging, shopping, learning and exploring.

We need to accept to simply replace what we are comfortable with, with something new; which does not enhance our experience, is simply not worth it!

Many of us, like Karen, would argue the experience of shopping is what the mobile phone can enhance and let the act of payment become the afterthought.  A simple click to say – yes, I agree to pay.

Amazon got it right with One Click.  Others, as the patent expires, are embracing the same technique to simplify payment to a friction-less act of satisfaction.  When my favorite stores offer me an mobile app designed to enhance my shopping experience, to thrill me with offers and entice me with things I want; then yes I will become more loyal, I will shop at their store more frequently and maybe even buy a few things I did not intend to buy.

Many years ago while attending conference of groceries  in Abu Dhabi – one of the speakers share an experience.  when that supermarket executive instructed each store to put the beer across from the diapers, the intended result occurred.  The husband, sent to get the diapers, ended up buying  a six pack too.

Maybe, like this experience reveals, if we focus on the consumer experience and on delighting them.  They will embrace change.

If there is no value why should we?

Years ago I prepared and published an idea.  I called it Cando.  I was still committed to the idea of the mobile wallet.  I was an early adopter of the smart phone and saw its potential.


Block Chain. Hype, the future, fiction or a scheme?

A month or so ago I was asked to speak to an assembly of bankers and processors at the Atlanta Federal Reserve on Cryptocurrencies and blockchain.

 Yesterday over a lunch I ended up synthesizing my thoughts into a neat little package that I would like to start sharing.

Those who extoll the virtues of Block Chain  speak of:

  • Immutability – Cryptographers and mathematicians will prove the immutability of the algorithms, at least for now
  • Distributed – as long as there a multiple diverse and competing stakeholders this is great
  • Trustless – I keep asking the same question Who defines the content of the Block or the ledger or the transaction?  Everyone ultimately agrees a body of people and I sit there and say that sounds like a governance model.  Be it a currency, a ledger, a contract two or more must agree to structure format, content and rules.
  • Consensus – Great as long as we never exceed the 51% participation by A party, the model is superb.

I then think about Work and the reward

Be it Proof of Work or Proof of Stake the entities that do the work are intermediaries and will want to be rewarded for their work.

Then one must think about shifting from a solution that rewards someone with a coin to a system that rewards someone with a fee earned.

I then reflect on Bit Coin and its use of Proof of Work

Coins are created by the party who figured out the Nonce, as a reward for solving the cryptographic puzzle.

  • Once they earned 25 Bitcoins
  • Today they earn 12.5 Bitcoins
  • At some point, in the future, the reward will be cut in half and then half again

The challenge

As the chain gets longer the work gets harder

As time moves forward and the number of coins in circulation grows

The reward decreases in notation value. 

Sounds like inflation is built in. 

Real estate, computers and electricity cost money. 

As the work expands the costs increases!

In conclusion

There is inherent Inflation built into the Bit Coin Model.

We simply replace intermediaries with Nodes and Miners.

We require a governance model so we simply change the governor to another.

People will want to be paid for the work they do to build the block or assure consensus of the chain

What is truly revolutionary? 

The math, ok maybe. 

Immutability, it is done today with cryptography, without a block chain.

Multiple copies of the ledger spread around the world.  Yes, as long as we address confidentiality.

We have governance, sure we can always elect a new government

What is so magical?


Federation and the Identity Provider

This year, one of many discussions I’ve been involved in revolved around these two foundational terms. In our digital environment and in support of an ever increasing array of people – individuals – engaging and interacting in the physical and virtual world, the questions – who are you and who can prove who you claim to be – becomes a critical element of establishing business and social relationships.

“Once Upon a Time” we lived in villages and knew our neighbors. When we travel afar, we would go with a letter of introduction from a Lord or other important, known and recognized person. A credential signed and sealed would assure safe passage and presented as. Proof of Identity upon arrival. Trusted identify established via a signed and sealed inside a Letter of Introduction.

Federation is a mechanism to convey a proof of identity in a digital world.

of Tokens and Things

Things, now there is a big word.

  • I am a thing
  • It is a thing
  • I know a thing
  • Things must therefore be anything

The dictionary rambles on about things.

Tokens, What is this thing?

Tokenization why is everyone so excited?

Tokenization and the Search for Identity

The belief in tokens emerges from the need to address security in a world where an identifier becomes an authenticator.

The PAN on the front of a ID-1 Card defined and governed by the International standard IS)/IEC 7812-1. When it was originally conceived there was no desire to turn the PAN into PII Data. They simply wanted the PAN to be an index, “a pointer” “an Identifier”, to an account, or relationship, a card issuer (financial institution) created between itself and the cardholder. In our quest to take advantage of the telephone, the mail and ultimately the internet as a set of sales channel. The Payment System actors agreed if the card acceptor “merchant” would accept liability. Then, they could simply use the PAN, the expiry data and cardholders name to effect a card payment. This acceptance of liability was an acknowledgement they could not inspect the card and verify that the physical security features where present, hence the token was not present to be authenticated.

Society in its infinite wisdom followed another path with the Social Security Number. A number originally designed to act simply as a unique value representing each person here in the United States. Unfortunately, as is often true, we took the short cut, assumed this number, stored on hundreds of databases and recorded on an equally large number of forms, could be used to authenticate that you the individual was present.

mysteriously and without thought society allowed these numbers to take on values they where never intended to assume. They became “secrets” number that if known to another could be used to take over our identity. They can make payments in our name. They can apply for loans and take over our financial assets without the true individual being the wiser.

Those that seek to profit and do not share societies morality find ways of taking advantages of our desire to cut cost and reduce friction. They create near perfect counterfeits of these tokens, they take advantage of our naivety and they seek to disrupt and profit.

We could do as we have often done in the past – replace the token with a token. We could claim by tokenizing these identifier with another vale we were adding layers of security. We argued that if this new tokenized value could only be used by that merchant or with that physical device; security would be restored. The question how long would that new think provide the security its champions claimed it would offer.

Payment Card Construct and Dual Interface Deployment

Payment Card Construction

The discussion focused on the construction of the sandwich. Four layers. Clear front laminate to protect the ink, front with the banks design and brand logo, back with the banks back design and a clear laminate with the magnetic stripe integrated into it.

To enhance design additional layers may be added, such a metal foil.

These four sheets are then bonded together, at 120 degrees, in sheets of 21, 36 or 48 or other various sheet sizes. Next step punch out cards, add hologram and signature panel.

For a standard EMV card the next phase is to mill and embed the module with the chip inside. Last, the manufacturer typically loads the O/S & EMV application into the integrated circuit card.

When we move to dual interface caed, this process is modified to add an inlay, with the antenna embedded within. This inlay is inserted in the middle of the sandwich and during the embedded process the contacts exposed on the base of the module are connected to the antenna in the inlay.

Next step, personalization, when the appropriate data is loaded into the chip, along with the encoding of the magnetic strip and printing and/or embossing of the cardholders, name, expiry date, cvv2 and other information onto the card.

Contactless or Not That is a Question

Contactless NFC acceptance and dual interface issuance is all about the chicken and the egg. Who will go first? The merchant or the issuer? Each need each other. Both are wondering about the incremental value.

  • Faster transactions – Yes
  • Less cash – maybe
  • More revenue – good question!
In other parts of the world, transit and their choice of contactless, as the right answer to a more efficient fare collection solution is driving conversion. In other, markets a group decision to adopt or a desire to find the next great thing drives the market. Here in the USA, we have a less than successful history of contactless. Let’s not forget PayPass and PayWave, it was tried the middle of the last decade, to little or no success.
We have Google and the FinTech world looking to mobile payments as the next great adventure. Merchants, like Wal-Mart, are resisting NFC acceptance given their own plans for QR based wallets and desire to limit the sharing of data with competitors.

Given these questions and observations, one can only wonder.

life, liberty and the pursuit of happiness

When I received this video

I wondered if prudish Americans would appreciate the continental humor.

For me and now I speak from my heart, mind and soul.  I remember well going to Jones Beach with two special ladies.  They made it clear they would bath as they wished and I needed to accept and not be some leering male.  I then remember traveling to Paris and seeing beautiful people adorning those typical French round advertising pillars.  The French simply use the beauty of the human body to promote perfume or some other sensual thing.  After I moved to Europe and we venturing, children in hand, to the beaches of Holland, France, Spain and Italy we learned to simply accept.  Even more telling, I attended an ITUG conference at a 5 star hotel in Budapest and ventured down to the spa.

I wonder why Americans  are bound up in a moral turpitude.

We are either far to the right or fair to the left.

Arnold Schwarzenegger was interviewed today and argued our country must come back to the center.  Morality is key to why we are so far apart.  So many on the right so many on the left.  Little room to find accommodation in the middle.

We purport to be a country of law, a country of freedom and a country of choice.  Yet we are tangled up in imposing rules to govern choice.  I read of how in Virginia back in the 30’s they attempted to ban interracial marriage and discovered that most of the population had some of Pocahontas in them.  I then think about those that are marching today.  They argue that the friends who died, are more important than the rights of those who want to let anyone bear arms.  Yet that small minority, the NRA, seems to have control over the decisions of the peoples’ representatives.  If we believe we can ban the mixing of races, yet we are unable, as the majority, to ban the type of arms, weapons, people are allowed to own, what are we!

Arnold today spoke of education, health and the environment.

If we want to Make America Great Again then why do we allow our system of education  to stigmatize people based on where they live.  Why do we not assure each citizen the right to equal education.  He reminded the audience this country ranks 39th in the world.  He said that regulating diversity was ridiculous.  He argued that by offering equal education, we enable people equal opportunity.  His argument made perfect sense.  Using local property taxes to fund education, ultimately means where you live, hence your family income, defines who has opportunity to excel.  If we want to remain the greatest country in the world and assure all citizens equal opportunity, then, we must invest in education.

Bottom line Education is the key to Making America Great Again.

Health, there are 4 living doctors in my family.  Through my kinship to them, I have heard and listened to them speak of the issues with our system.  For my simple mind the problem begins with Capitalism.  It is all about big corporations wanting to profit from their skills.  It is about insurance companies wanting to minimize risk (expense) by minimizing the amount of care they have to pay for.  I am familiar with social medicine.  Three countries provided me personally with exposure to how it can and does work.

Yes, if you can afford care in this country, you will get the best care.

The challenge, every American cannot afford care, without insurance.  And, if everyone is not insured then those that are the least wealthy and healthy are without.  For me this graph tells the whole store. 
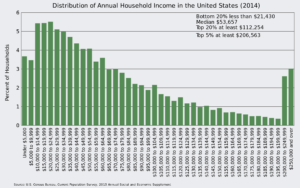
I am personally paying insurance under a Cobra plan.  For Selma and I, one household, it costs 1,291.43 a month $15,520.92 a year.

We all need universal care.  We need to require everyone to pay into our health system.  This is the only way will we assure affordable care for all.  How does one build such a system, I suggest, it must resemble what Switzerland has built.

Minimum care paid through taxes.  Supplemental care, each households responsibility.

Next is our environment.  Once, we worried about pollution and the quality of our air and water.  Now, we must expand our thinking.  We must remember we are stewards of this earth and realize our consumption of the earth’s resources will affect the balance of the earth and its ecosystem.  We are here to protect the earth for our children and for the children they will bring into this world.

We can argue all night long about the science.  What we do know is that if we change the balance of anything there is a result.  The classic appreciation of cause and effect.  We the USA, with less than 20% of the word population, recently were responsible for most of the carbon dioxide injected into the atmosphere.  Today this no longer is true.  But, we recently pulled away from helping to lead the world to a better place.  Instead our President wants us to return our sources of energy back to those non renewable earthly resources, coal and oil.  We all know they pollute!

Finding reusable means of generating energy, is good politics.  The Economist March 17th 2018 had an excellent special report on the politics of energy.

If we do not embrace renewable sources of energy and reduce our dependence on Oil and Coal, we will no longer be the great national we are and seek to remain.

As I write, I am remember learning about the Fourth Industrial Revolution.  As the first sentence so aptly says it

“The Fourth Industrial Revolution is changing everything – from the way we relate to each other, to the way our economies work, to what it means to be human”.

We must properly harness technology.

  • Education is the key.
  • Our environment can only benefit.
  • Healthcare will simply become more efficient

In the end we will improve everyone’s life.

Yet?

As Adam Smith best explains, our global economy (yes we are a global economy), can only be successful when we view it as a closed system.

We must appreciate that we are all part of the whole.  Only when we each give to our own abilities, will we find balance.  If we allow labor arbitrage to take jobs away; then, those who lose their jobs must find new ways to contribute.  They cannot expect the system to sustain them!

Yet they should expect those that profit to help re-educate.

Why am I writing.  What am I asking.

Maybe to share.  Maybe to speak out.

There is one other topic on my mind.  Those who understand the loss of a friend in Parkland are speaking out, they are marching in Washington and around the country to get people to listen and vote to arrest the stupidity of how the second amendment is being mis-interpreted.

For me the key is found in the first part of that amendment

“ A well regulated Militia, being necessary to the security of a free State,

In my opinion, what resulted from  District of Columbia v Heller (2008) was an unreasonable interpretation of the second amendment.  I would suggest United States V. Cruikshank (1876) and United States v Miller (1939) are a better interpretations.  Those interpretations, in my opinion, are not influenced by the political influence of the NRA and gun manufactures’.  Their and the NRA’s focus is to market, sell and protect their right to profit!  They are not focused on assuring the free state has a well regulated militia.  If they were, they would insist on training, education and the formation of groups – in other words militias.

The second phrase

“The right of the people to keep and bear arms shall not be infringed.”

For me, this is why Switzerland ends up with guns in every home.  The people are members of the armed forces. They are “The Militia”.  They belong to a “well regulated” group of people focused on “the security of a free state”.  They are trained.  They understand the purpose of these weapons.  The militia, in other words the people, can determine if there are mental issues and exclude those individuals as they are evaluated and introduced to their responsibility as a member of the militia of the people.

Looking back on the histogram above many of you are or will be part of the upper 10%.  We are the ones most gifted.  We therefore must be the ones that are the most interested in making this world is a better place.  Simply accepting the way it is, means we are not working together to make the world, this country, a better and more equal place.

Going back to the video we must assure our freedoms.  We must focus not on how we expect people to live.  We must remember why we became a nation.

“We hold these truths to be self-evident, that all men are created equal, that they are endowed by their Creator with certain unalienable Rights, that among these are Life, Liberty and the pursuit of Happiness. — That to secure these rights, Governments are instituted among Men, deriving their just powers from the consent of the governed”

Our founders made it clear, we each have the right to life, liberty and the pursuit of happiness.

The way I interpret what we attempted, as a nation, to establish; is a body of people, a society, that respects each of our individual rights and seeks to protect each individuals right to life, liberty and the pursuit of happiness.  If I want to expose myself in the comfort of a community that enjoys this way of life, as long as we do not imping on your rights, why not?  Slavery, Blue laws, various interpretations based on the desire to impose your will on me is not why we declared independence.  It is not what our constitution attempted to create.

I want clean air, clean water, not to see your litter in public view and be able  to drink alcohol and/or smoke marijuana.  I want the ability to see a doctor when I need to and not worry that I cannot afford to.  I want to be able to to see all children attend school, knowing they will get a great education.  I also do not want to worry that some lunatic will buy assault rifles and use these weapons reserved for a well regulated militia to kill children while they are at school.  I want to be able to attend a music festival and not worry that some person up in some hotel room is capable of buying an arsenal simply to kill people.

Yes we should have the right to hunt and protect ourselves.  Assuming we are trained and capable and more importantly are of stable mind and body.

We must each remember the ten commandments Exodus 20 or simply put the two found in Matthew 22:37-40, Mark 12:29-34 and Luke 10:25-37

Most importantly we must read, appreciate and be the Samaritan described in Luke 12:30-37.

Each of us is bestowed with skills and abilities.  We have the funds to be able to help drive policy we have the responsibility to assure each is given the right to life, liberty and the pursuit of happiness.

These are my beliefs.

I hope those reading my thoughts are willing to respect them and share theirs.  Only if we engage in discourse can we assure ourselves life, liberty and the ability to pursue happiness.

Obviously to avoid spam I do moderate comments.  As long as there is no profanity, I will not censor anyone’s comments.  I am also posting the existence of this Blog on Twitter and Facebook.  In those environments and as Cambridge Analytica has demonstrated, these thoughts will simply expand the public’s awareness of my habits, patterns and thinking.

Respectfully,
 

Financial Trade Groups Write to House Leaders in Support of Data Breach Notification Bill

https://bankingjournal.aba.com/2018/02/financial-trade-groups-write-to-house-leaders-in-support-of-data-breach-notification-bill/

 The American Bankers Association and six other financial trade organizations wrote to House leaders today underscoring the need for businesses across all industries to be held to the same data protection and breach notification standards currently adhered to by regulated financial institutions.

The associations expressed support for draft legislation released by Reps. Blaine Luetkemeyer (R-Mo.) and Carolyn Maloney (D-N.Y.) that would create a level playing field of nationally consistent data protection standards and post-breach notification requirements. This bill would not create duplicative standards for financial institutions which are already subject to robust standards, but rather extend similar expectations to other sectors that handle consumer data.

“The goal of the bill is simple — raise the bar so that all companies protect data similar to how banks and credit unions protect their data, and create a common-sense standard to ensure consumers receive timely notice when a breach does occur,” the groups wrote.

The draft bill contains a provision that recognizes the existing, effective regulatory framework for covered financial sector entities.  While the provision was intended to prevent banks and credit unions from being subject to duplicative notification requirements, it has been the target of recent negative campaigns circulated by the National Retail Federation and the Retail Industry Leaders Association, which incorrectly suggested that banks do not notify customers of breaches on their computer systems and   The ads from the retailer groups also mischaracterize and exaggerate the share of data breaches occurring at banks and credit unions while omitting their members’ (higher) share of data breaches.

The financial trades refuted the notification assertion, noting that “banks and credit unions have long been subject to rigorous data protection and breach notification practices for financial institutions to follow,” and that in the event of a data breach, banks and credit unions work continuously to communicate with customers, reissue cards and enact measures to mitigate the effects of fraud. They added, however, that “no solution will work unless everyone has an obligation to take these steps.” For more information, contact ABA’s Jess Sharp.

What scares me most

Tonight while preparing to listen to the Atlanta Symphony Orchestra play a bit of Beethoven I have a moment to reflect on the Worldview.

Once upon a time one could turn on the news and get a glimpse of what is happening at home and round the world. One could pick up a newspaper and think this will provide me a glimpse of the truth.

Then! In emerged the capabilities of communications and the capacity to write and distribute anything to a vast number of individuals. Otherwise called the Internet.

Yet, what is different? In the past books were burned, history was rewritten and lies were told. The challenge,today we can manipulate what people believe, on a global scale, in realtime. We can spread disinformation and drive the masses to believe anything people with a voice and the power to thrill want to convince them to believe.

Starting in 2016 who would become the American President proved this to be possible. The media demonstrated that they can spin the truth in whatever direction they so desire.

This week the story is about how the DOJ and the FBI obtained warrants from one of the strictest courts in the land. Every 90 days bringing new information, they convinced the FISA court to allow them to continue to investigate the potential actions of our enemy, Russia, or, what was the USSR. What the Russians did was evil and manipulative. I somehow doubt the GOP’s version of the trutb.

Vindicated! Donald thinks he is. Yet, for those who take the minutes to read, one can only wonder what does this incomplete review of the facts actually prove? Nothing!

I wonder why I waste so much of my time listening, reading and worrying. Is there truly a risk? Are we so divided that it matters. Maybe!

Part of the challenge, many think President Trump is doing good. They accept his narcissistic personality and read his tweets with a simply, oh please stop. The rest of us cringe and worry. We consider the risks. We watch our leaders splinter and the divide expand, and we hope for a better day tomorrow.

Fir thise that seek out the truth, we explore and we become aware of the elements that are driving us into the Fourth Industrial Revolution. It causes us to wonder what can we do to bring the masses, those unskilled workers, who have been marginalized by intelligent robots, programmers, engineers and managers out of desolate. We work to reduce the numbers of workers and expand productivity all while ignoring the realities of the human repercussion ahead.

When I started this note, the thinking was about those who do not accept science, believe the world is flat and maybe 9,000 years old. They do not accept, we human kind, are responsible for the wrath of our planet’s climate. They do not appreciate the dangers ahead, as we change the balance of our atmosphere and pollute the lands and oceans that sustain us.

What next?

The management of our identity

A few weeks ago I learned of the Sovrin Foundation a foundation interested in establish a concept to support the idea of a self Sovereign means of identity.

As an advocate for stronger forms of identification and more important Authentication I am pleased to have received your response today.

Back in 1993 I was part of Europay and drove the creation of the EMV specifications as a form of Authentication and frankly reflecting back a strong form of Identification with the Trust Anchor being the Financial institution issuing the card and the foundation anchor being the payment network that the issuer used to assure acceptance globally.

In 2013 I joined the Board of the FIDO Alliance and eventually become the Secretary of that Board.

Today I am engaged with a company called IPSIDY, that is promoting and selling Identity as a solution.

Clear the conversations we are having include:

  • Device based versus centralized biometric authentication
  • Identification based on a central repository of Biometrics or a simply identifier linked to a means of authentication
  • Claims and assertions one points (URL) to or those that one has in their own possession
  • Repositories or Distributed databases of information
  • Privacy of attributes and rights to defining what can be shared

When I ask about the future of Sovrin, I hear people saying great concept how does it scale to be useful. 

This, as was my experience in the Payments world, is the challenge of a  two sided market

  • Consumer – Merchant
  • Individual – Rely Party and those seeking attributes and proofs of identity

The challenge is developing a value proposition and more importantly critical mass that will excite both sides of the market to want to participate.

To further complicate developing the market is the challenge of the “Go To Market” strategy.  Who does one partner with given that the usefulness to the citizen/consumer is predicated on the number of parties or places this solution, token or Identity with a set of sharable attributes can be usefully used.


This is the question this is the challenge.


A Shift from Check-out to Check-in will reshape the way merchants engage with their consumers

Think Uber, think order ahead, think account on file. With these ideas in your mind think engagement and Omni channel. Then consider the need of merchants to assure revenue by delighting and engaging with their customers in meaningful ways. Their focus, increasing basket size, more frequent visits and loyalty; in other words increased sales.

Then remember, Check-out is about friction, payments and long lines. These characteristics merchants seek to eliminate, reduce the cost of and enhance the experience around.

If we think Check-in, using big-data, geo-location, BLE, facial recognition, consumer centric apps and other techniques, we can image a world where human and device based personal assistants engage with the merchants loyal customers in a friendly, informed and satisfying way.

For payment people this means we need to remember that merchants want lower cost payments and friction-less check-out.

Bottom line, for loyal customers solutions that retain the payment credentials securely in the cloud. For one time and infrequent customers, they will look to incent loyalty and registration or simply accept classic means of payments e.g. cards.

This drive to move from recording a loyal customers visit to engaging when the customer arrives or better yet when they are doing their research is what we the consumer seek.

We are all about saving time, enjoying life and satisfying our needs and wants. Merchants that focus on the customer and their shopping experience will succeed and prosper./ Those that do not focus on delighting their customer will learn.

DIY the Cyber Guy a conversation about Bitcoin and EMV 

https://www.voiceamerica.com/promo/episode/104814

A interesting discussion withDavid the the Cyber Guy.  We spoke of the inherent risk of Bitcoins and the essential issue of the secret and a BitCoin folders resoponsibility to make sure they never lose the secret.

We then wandering off to talk about EMV or Chip and Pin.

Always a pleasure to work with David.

Words all bound to who we claim to be – How do we identify ourselves on the Internet or in Cyberspace?

Identifier – Something you create or are provided to digitally identify yourselves. Identifiers are things like an alias, user name, email address are examples.

Identity – This is who we are or wish to represent ourselves to be. These are attributes and information about: where we live, who we work for, which banks we have relationships with, who our friends are, which clubs we belong to, our certified skills, what schools we graduated from, which country(s) we are citizens of, our LinkedIn profile, Our Twitter handle, our Facebook identifier, our phone number … .  It is the sum of the attributes we can and will share with others, be they individuals, governments, entities or organizations; as we establish relationships and prove to them who and often what we are.

Authentication – The method we employ to assure that you, based on the identifier presented, are who we (the relying parties) thinks you are.  You are the person the relying party accepted when you registered that Identifier as how you would digitally identify yourself.  By itself the method of authentication should not allow another party to be able to determine anything about your identity.  Privacy is the goal.  FIDO Alliance and W3C have defined standards to support authentication.

Verification – The process of confirming that the secret or biometric match the secret or biometric that where originally registered to that Identifier.

Identification – A means of authentication that is bound to your identity.  A EMV payment instrument “Chip and PIN”, a PIV card, an electronic passport, a membership card, a drivers license, a national ID are all forms of identification  issued by a party that should be trusted to have performed a proof of the individuals Identity, based on a defined and often published criteria.

This particular word, for many, has an alternate meaning.  In the biometric community they see Identification as the ability to use a biometric to determine ones Identity.  This is achieved by performing a one (the person present) to many match (persons registered).  The goal is the same, bind Identity to the mean of Authentication by using the Biometric as the Identifier.

Proof – The method a relying party or an individual uses to validate your claim of a specific Identity.  In many cases this is achieved by relying on knowledge of another party.  The relying party accepts the due diligence to proof your claimed identity was done to their satisfaction by another party.  This other party is often referred to as a Trusted party.  This effort to proof the identity of an individual is linked to words and acronyms like KYC “Know Your Customer”, ID&V “Identity and Verification” and Self Sovereign Identity.  We classically assume that documents provided by a Government e.g. drivers License and Passports are a solid proof of the claims asserted on those same documents.

In a digital world this is the most important element of a how we as people, entities, governments and corporations can be assured that you are who we believe you to be.

I am once again am reminded of the 1994 New Yorker Cartoon